


Published as part of the ECB Economic Bulletin, Issue 6/2026.
This box reviews the Eurosystem liquidity conditions and monetary policy operations in the third and fourth reserve maintenance periods of 2026. Together, these two maintenance periods ran from 6 May to 28 July 2026 (the “review period”).
Average excess liquidity in the euro area banking system continued to decline. Liquidity provision decreased over the review period, owing primarily to lower Eurosystem holdings under the asset purchase programme (APP) and the pandemic emergency purchase programme (PEPP) following the discontinuation of APP reinvestments at the beginning of July 2023 and PEPP reinvestments at the end of December 2024. An increase in net autonomous factors also contributed to the overall reduction in excess liquidity.
Liquidity needs
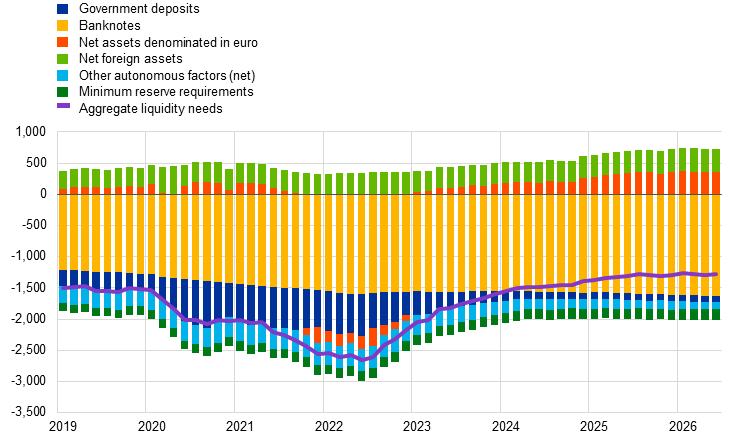
The average daily liquidity needs of the euro area banking system, defined as the sum of net autonomous factors and reserve requirements, increased by €11 billion to €1,284 billion over the review period (Table A). The higher level of liquidity needs was driven by a rise in net autonomous factors, mainly reflecting a decline in liquidity-providing autonomous factors (Table A). Minimum reserve requirements rose by €2 billion to €174 billion, also contributing to the increase in liquidity needs.
Chart A
Aggregate liquidity needs by reserve maintenance period
(EUR billions)
Source: ECB.
Notes: Each bar shows the averages for each maintenance period. There are eight maintenance periods a year, with the eighth period extending into the following calendar year. The latest observations are for the fourth maintenance period of 2026.
Liquidity-providing autonomous factors declined by €11 billion over the review period, owing primarily to a decrease of €15 billion in net assets denominated in euro. This reduction was attributable to a rise in euro-denominated non-monetary policy deposits, which are liquidity-absorbing. At the same time, net foreign asset holdings increased by €4 billion, partly offsetting the decline in liquidity-providing autonomous factors.
Liquidity-absorbing autonomous factors decreased more modestly by €2 billion over the review period. This reflected an increase of €16 billion in the average value of banknotes in circulation, which was more than offset by declines of €10 billion in net other autonomous factors and €8 billion in government deposits held with the Eurosystem.
Liquidity provided through monetary policy instruments
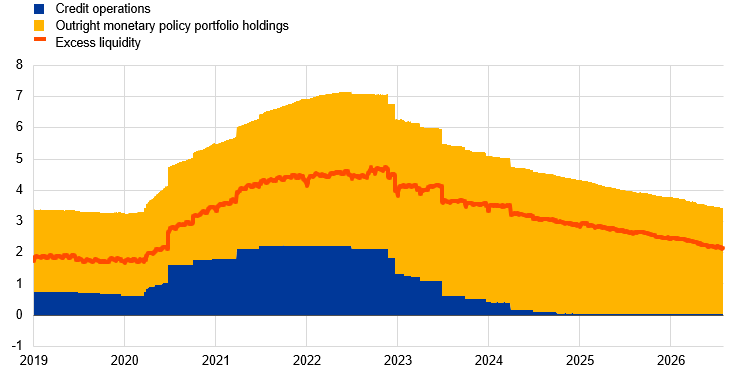
The average amount of liquidity provided through monetary policy instruments fell by €147 billion to €3,485 billion over the review period (Chart B). This decrease in liquidity provision was primarily due to a €150 billion reduction in Eurosystem outright monetary policy portfolio holdings, following the continued redemption of APP and PEPP holdings in the absence of reinvestment. As a result, the amount of liquidity provided by these portfolios declined to €3,458 billion over the review period.
Chart B
Liquidity provided through open market operations and excess liquidity
(EUR trillions)
Source: ECB.
Note: The latest observations are for the fourth maintenance period of 2026.
The average amount of liquidity provided through credit operations increased by €3 billion to €27 billion over the review period. The average outstanding amounts of main refinancing operations (MROs) and three-month longer-term refinancing operations (LTROs) rose by €1 billion and €2 billion respectively. Participation in these regular operations remained limited, reflecting the ample liquidity position of banks and the ready availability of alternative market-based funding sources. However, the number of banks testing the viability of their participation has continued to grow in 2026, indicating that they are building up their operational readiness to access these operations.
Excess liquidity
Excess liquidity fell by €157 billion to €2,201 billion over the review period (Chart B). Excess liquidity is the sum of the reserves that banks hold in their current accounts in excess of the minimum reserve requirements and their recourse to the deposit facility net of their recourse to the marginal lending facility. It reflects the difference between the total liquidity provided to the banking system via monetary policy instruments and the liquidity needed by banks to cover their minimum reserves. Having peaked at €4,748 billion in November 2022, excess liquidity has declined steadily.
Interest rate developments
During the review period, the Governing Council raised the three key ECB interest rates by 25 basis points, including the deposit facility rate through which it steers the monetary policy stance. Following this increase, the rates on the deposit facility, MROs and the marginal lending facility stood at 2.25%, 2.40% and 2.65% respectively (Table B).
The average euro short-term rate (€STR) rose by 25 basis points over the review period, in line with the increase in the deposit facility rate. On average, the €STR remained 6.8 basis points below the deposit facility rate over the review period, unchanged from the first and second maintenance periods of 2026.
The average euro repo rate, as measured by the RepoFunds Rate Euro index, remained closer to the deposit facility rate than the €STR did over the same period. On average, the repo rate exceeded the deposit facility rate by 1.6 basis points, up from 0.7 basis points in the previous review period.
Table A
Eurosystem liquidity conditions
(averages; EUR billions)
Source: ECB.
Notes: All figures in the table are rounded to the nearest €1 billion. Figures in parentheses denote the change from the previous review or maintenance period. MROs stands for main refinancing operations and LTROs for longer-term refinancing operations. The historical time series of Eurosystem liquidity conditions can be found in the ECB Data Portal under the table tab of the liquidity report.
1) Memo item that does not appear on the Eurosystem balance sheet and should therefore not be included in the calculation of total liabilities.
2) Computed as the sum of current accounts above minimum reserve requirements and the recourse to the deposit facility minus the recourse to the marginal lending facility.
3) Computed as the sum of net autonomous factors and minimum reserve requirements.
4) Computed as the difference between autonomous liquidity factors on the liabilities side and autonomous liquidity factors on the assets side.
Table B
Interest rate developments
(averages; percentages and percentage points)
Sources: ECB, CME Group and Bloomberg Finance L.P.
Notes: Figures in parentheses denote the change in percentage points from the previous review or maintenance period. MROs stands for main refinancing operations and €STR for euro short-term rate.